Understanding how capital gains are taxed may help you refine your investment strategies.

Chris Rock once remarked, “You don’t pay taxes – they take taxes.” That applies not only to income but also to capital gains.

Capital gains result when an individual sells an investment for an amount greater than their purchase price. Capital gains are categorized as short-term gains (a gain realized on an asset held one year or less) or long-term gains (a gain realized on an asset held longer than one year).

Keep in mind that the information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation.

Long-Term vs. Short-Term Gains

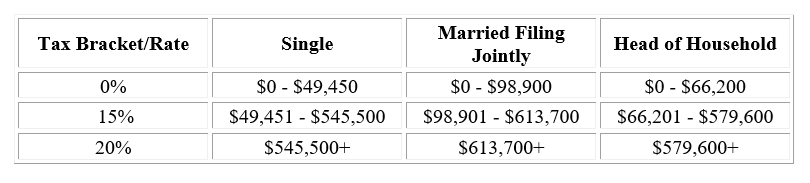
Short-term capital gains are taxed at ordinary income tax rates. Long-term capital gains are taxed according to different ranges (shown below).1

Long Term Capital Gains Tax Brackets (for 2025)

It should also be noted that taxpayers whose adjusted gross income is in excess of $200,000 (single filers or heads of household) or $250,000 (joint filers) may be subject to an additional 3.8% tax as a net investment income tax.2

Also, keep in mind that the long-term capital gains rate for collectibles and precious metals remains at a maximum of 28%.3

Rules for Capital Losses

Capital losses may be used to offset capital gains. If the losses exceed the gains, up to $3,000 of those losses may be used to offset the taxes on other kinds of income. Should you have more than $3,000 in such capital losses, you may be able to carry the losses forward. You can continue to carry forward these losses until such time that future realized gains exhaust them. Under current law, the ability to carry these losses forward is lost only on death.4

Finally, for some assets, the calculation of a capital gain or loss may not be as simple and straightforward as it sounds. As with any matter dealing with taxes, individuals are encouraged to seek the counsel of a tax professional before making any tax-related decisions.

1. IRS.gov, 2025
2. IRS.gov, 2025
3. IRS.gov, 2025
4. IRS.gov, 2025
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

In investments, one great debate asks the question, “Active or Passive Investing: Which Is Better?”

Whether it’s sports, music, or politics, life holds any number of “great debates”– debates that never seem to reach a conclusion. In investments, that great debate asks the question, “Active or Passive Investing: Which is Better?”

The fascinating aspect of this debate is that equally intelligent people can argue polar opposite positions, leaving the rest of us to wonder what the answer is, if one even exists.

Passive Pointers

The case for passive management is anchored in the evidence that the preponderance of money managers have failed consistently to beat their comparative index. This is true for two primary reasons:

1. Markets are efficient and all known information is already reflected in the price of the stock, making it difficult for managers to find companies that are expected to outperform.1
2. The hurdle of an elevated expense ratio typical of actively managed mutual funds makes it hard to match or exceed a low-expense index fund.

Active Arguments

Active managers counter that while the markets may be generally efficient, there are windows of inefficiency created by the time it takes for information to properly reflect in a stock’s price.

Active managers further argue that performance is not just about relative return, but also about managing risk. For instance, if an active manager can deliver a hypothetical 90 percent of the index return at 70 percent of its risk, then that constitutes a measure of outperformance.2

Unlock the Combination

Ultimately, it’s a decision based on what you want to pursue. Do you prefer the approach taken by index funds or the strategy behind active management? For some, the combination of both funds represents an approach that takes no sides but seeks to tap into the distinctive benefits each offers.

Mutual funds are sold only by prospectus. Please consider the charges, risks, expenses and investment objectives carefully before investing. A prospectus containing this and other information about the investment company can be obtained from your financial professional. Read it carefully before you invest or send money.

International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risk unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.

1. Keep in mind that the return and principal value of stock prices will fluctuate as market conditions change. And shares, when sold, may be worth more or less than their original cost.
2. This is a hypothetical example used for illustrative purposes only. It is not representative of any specific investment or combination of investments.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.
Understanding the economy’s cycles can help put current business conditions in better perspective.

What has upswings and downturns, troughs, peaks, and plateaus? Though such terms could easily describe a roller coaster ride, they are also commonly used to describe the business cycle.

The business cycle – also known as the economic cycle – refers to fluctuations in economic activity over several months or years. Tracking the cycle helps professionals forecast the direction of the economy. The National Bureau of Economic Research makes official declarations about the economic cycle based on specific factors, including the growth of the gross domestic product, household income, and employment rates.

Recovery & Recession

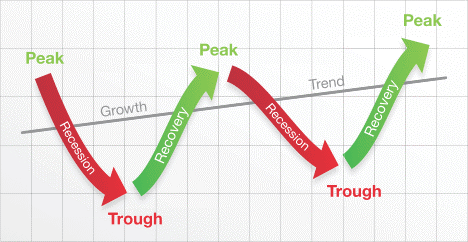
An upswing, or recovery, occurs when the economic indicators improve over time. A recession occurs when the same indicators go through a contraction. A particularly long or severe recession is referred to as a depression.

Despite being called a cycle, it’s important to understand that the business cycle is not regular or even cyclical. Its pattern resembles the movement of waves, and those waves don’t consistently undulate at set, periodic intervals. Some recoveries have lasted several years, while others are measured in months. Recessions, too, can last for a number of years or be as short as a few months.

Moving in Waves

Business Waves

Stages of Cycle

So, how should investors look at information about the business cycle?

Investors who understand that the economy moves through periods of recovery and recession may have a better perspective on the overall cycle. During recovery, understanding whether the economy is at an early or late stage of the cycle may influence certain investment decisions. Conversely, during a recession, deciphering whether the economy is passing through a shallow or deep cycle may be influential as well.

The business cycle will transition from recovery to recession – and recession to recovery – over several months. Understanding that the economy travels through cycles may help you put current business conditions in better perspective.

The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

This short, informative article teaches the basics of the FIRE movement.

If the idea of retiring in your early 50s, 40s, 30s, or even late 20s appeals to you, you may be interested in joining the FIRE retirement movement. Designed for those who have the discipline and cash flow to save diligently, FIRE can be an effective path toward living a work-optional lifestyle. In this article, we will discuss what FIRE is and whether or not it may be right for you.

What is FIRE?

FIRE stands for “Financial Independence, Retire Early.” This program, inspired by Vicki Robin’s book “Your Money or Your Life,” is built on the premise of saving more money month-to-month than traditional retirement approaches and utilizing low-fee investment choices to be able to afford retirement earlier than the traditional age.1

The “financial independence” portion of FIRE is considered to be about 25 times your yearly expenses. For example, if you decided you’d need $50,000 a year to live off of in retirement, you would need to save 50,000 x 25, or $1.25 million to be considered financially independent. Once that number has been met, you’d be able to retire and enjoy a life of financial freedom, withdrawing about three or four percent from your nest egg each year.

Top Considerations Before Joining the FIRE Movement

Retiring in your 30s may sound too good to be true. In fact, the whole FIRE movement and premise of retiring early can sound like more of a daydream than reality. And for some, it may be just that. But for others who are able or willing to embrace the lifestyle, financial independence early in life can be possible. Here are a few important considerations to make before deciding if the FIRE program may be right for you.

Consideration #1: You’ll Need to Spend Wisely

The big factors of the FIRE program are income, expenses, and time. The idea being, the bigger the gap between income and expenses, the less time it will take you to reach financial independence. And while it may sound extreme, depending on your timeline and desired income level in retirement, you could be looking to save more than half of your income to put toward early retirement. This is something that would need to be calculated individually, as it is based on your income level and current expenses.

However, living a frugal lifestyle now is almost always a universal requirement of the FIRE program and other early retirement seekers.

Consideration #2: FIRE Followers Don’t Embrace Traditional Retirement

For those looking to retire early using the FIRE method, “retirement” doesn’t mean sitting around and doing nothing. FIRE followers are typically more focused on the first part of the acronym, “financial independence,” than they are on retiring early. That means that they’re likely to still work in retirement or pursue a passion project they were previously unable to due to the confines of a full-time job.

Consideration #3: You’ll Want a “Why”

Like many financial goals, it can be hard to find the motivation to skip dinners out or splurging on a new outfit. When you have a nondescript idea of retiring early, there’s little motivation to skip out on some enjoyment today for the possibility of an early retirement a decade down the line. Instead, those who have embraced the FIRE method often put a “why” to their savings programs, and it’s important to get as specific as possible. Define your “why” and let it guide you in making positive progress toward your financial independence.

The FIRE program is an appealing method of reaching retirement early on in life and allows for its followers to find the flexibility in doing what they love. It does, however, take self-discipline and the ability to spend less today in order to save for tomorrow. If you’re considering the FIRE method, it may be wise to work with a financial professional who can help you understand your current spending habits and what you’ll need in order to find financial independence for an early retirement.

1. Vickirobin.com, 2023
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Learn the advantages of a Net Unrealized Appreciation strategy with this helpful article.

Employer-issued stocks can be one attractive benefit an employer can offer. But while it has its benefits, it’s natural to wonder what happens if you leave that job.

That’s where net unrealized appreciation (NUA) strategies can sometimes be helpful. An understanding of NUA strategies can help you determine what to do with those company stocks to potentially manage your tax bill.

Remember, this article is for informational purposes only and is not a replacement for real-life advice. Make sure to consult your tax professional before modifying your approach with any unrealized appreciation issues.

Once your tax professional has provided guidance, your financial professional can offer insights regarding your overall asset allocation if you decide to realize any gains. Asset allocation is an approach to help manage investment risk. Asset allocation does not guarantee against investment loss.

What is Net Unrealized Appreciation (NUA)?

NUA is the difference between how much you paid or contributed to your company stock and its current market value. For example, if you were issued employer stock at $20 per share and it is now worth $50 per share, you would have an NUA of $30 per share ($50 – $20 = $30).

What are the NUA Rules?

Your NUA may be taxed differently than other payments. If the lump-sum distribution includes employer securities, the NUA may not be subject to tax until you sell the securities.1

With this in mind, a participant may be able to transfer company stock from their previous plan into a taxable investment account without treating the entire amount as ordinary income. But before exploring any choice in detail, seek the guidance of a tax professional while keeping your financial professional apprised of your decisions.

1.IRS.gov, January 23, 2023
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Understanding the value of a home warranty.

As a consumer, when you purchase an expensive item, like a car or refrigerator, you expect to receive a warranty that the manufacturer will repair or replace that product if it breaks down.

A warranty makes sense for big-ticket purchases, but what about for a home?

An Overview of Home Warranties

A home warranty typically covers the repairs on specific items in a home, such as heating and air conditioning systems, plumbing, and built-in appliances.1

A home warranty on a newly built home may be offered by the homebuilder and may cover up to 10 years on structural defects; one year on items like walls and paint; and two years for HVAC, plumbing, and electrical systems. Appliances may only be covered for six months. Typically, the cost of this policy is contained in the price of the home.

A home warranty on an existing home can also be purchased, usually paid for by the seller or real estate agent to facilitate the sale of a house. These policies tend to have coverage lasting no longer than one year.

Occasionally, a home buyer may choose to purchase a policy, for instance, in the case of buying a foreclosure.

Be Realistic

You should understand the limits to which a home warranty can protect you. A home warranty promises you that certain items will remain functional; it does not promise you a new appliance or furnace.

Though it may be comforting to know repairs are covered, a warranty may restrict the contractors you can use to do the repair work.

A home warranty may be most beneficial to someone who will be purchasing an older home.

If you elect to buy a home warranty, make sure you work with a reputable company that has a long-standing record in your local area. And as always, be sure to comparison shop.

1. Several factors will affect the cost of a home warranty policy, including the size, location, and contents in the home. Any guarantees associated with a home warranty policy are dependent on the ability of the issuing company to continue making claim payments.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.
css.php