Learn all about Medicare basics in this informative and insightful article.

Medicare is the federal government program that provides health care coverage (health insurance) if you are 65+, under 65 and receiving Social Security Disability Insurance (SSDI) for a certain amount of time, or under 65 and with End-Stage Renal Disease (ESRD). The Centers for Medicare & Medicaid Services (CMS) is the federal agency that runs Medicare. The program is funded in part by Social Security and Medicare taxes you pay on your income, in part through premiums that people with Medicare pay, and in part by the federal budget.

Once you have become Medicare-eligible and enroll, you can choose to get your Medicare benefits from Original Medicare, the traditional fee-for-service program offered directly through the federal government, or from a Medicare Advantage Plan, a type of private insurance offered by companies that contract with Medicare (the federal government). Original Medicare includes:

  • Part A (Inpatient/hospital coverage)
  • Part B (Outpatient/medical coverage)

If you want Medicare prescription drug coverage (Part D) with Original Medicare, in most cases you will need to actively choose and join a stand-alone Medicare private drug plan (PDP).

You still have Medicare if you enroll in a Medicare Advantage Plan. This means that you will still owe a monthly Part B premium (and your Part A premium, if you have one). Each Medicare Advantage Plan must provide all Part A and Part B services covered by Original Medicare, but can do so with different rules, costs, and restrictions that can affect how and when you receive care. Medicare Advantage Plans can also provide Part D coverage. Note that if you have health coverage from a union or current or former employer when you become eligible for Medicare, you may automatically be enrolled in a Medicare Advantage Plan that they sponsor. You have the choice to stay with this plan, switch to Original Medicare, or enroll in a different Medicare Advantage Plan, but you should speak with your employer/union before making any change.

It is important to understand your Medicare coverage choices and to pick your coverage carefully. How you choose to get your benefits and who you get them from can affect your out-of-pocket costs and where you can get your care. For instance, in Original Medicare, you are covered to go to nearly all doctors and hospitals in the country. Medicare Advantage Plans, on the other hand, usually have network restrictions, meaning that you will be more limited in your access to doctors and hospitals. However, Medicare Advantage Plans can also provide additional benefits that Original Medicare does not cover, such as routine vision or dental care.

Medicare is different from Medicaid, which is another government program that provides health insurance. Medicaid is funded and run by the federal government in partnership with states to cover people with limited incomes. Depending on the state, Medicaid can be available to people below a certain income level who meet other criteria (e.g., age, disability status, pregnancy) or be available to all people below a certain income level. Remember, unlike Medicaid, Medicare eligibility does not depend on income. Also, eligible individuals can have both Medicare and Medicaid and are known as dual-eligibles.

Everyone who has Medicare receives a red, white, and blue Original Medicare card. If you choose to receive your coverage through Original Medicare, you will show this card when you get services. If you choose to receive your Medicare benefits through a Medicare Advantage Plan, you will still get an Original Medicare card but you will show your Medicare Advantage Plan card when you get services. No matter how you get your Medicare health benefits, only give your Medicare number to your doctors and health care providers.

© Medicare Rights Center. Used with permission.

The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Here are five facts about Social Security that are important to keep in mind.

Social Security can be complicated, and as a result, many individuals don’t have a full understanding of the choices they may have. Here are five facts about Social Security that are important to keep in mind.

1. Social Security Is a Critical Source of Retirement Income

Some have the perception that Social Security is of secondary or even tertiary importance in retirement. But according to a recent report by the Employee Benefits Research Institute, Social Security represents a major source of income for 62% of retirees.1

Keep in mind that Social Security makes annual cost-of-living adjustments (COLAs) based on the Consumer Price Index, and under current laws, pays income for life and the life of your spouse.2

2. You Can Choose When You Take Social Security

You have considerable flexibility regarding when you can begin receiving your benefits. You may begin receiving benefits as early as age 62; however, your benefits will be reduced at a rate of about one-half of 1% for each month you begin taking Social Security before your full retirement age.3

The full retirement age is 67 if you were born in 1960 or later. If you were born before 1960, your retirement age will be reduced depending on the year in which you were born.

You may choose to delay receiving benefits until after reaching your full retirement age; in which case, your benefits are scheduled to increase by 8% annually. This increase under current law will be automatically added each month from the moment you reach full retirement age until you start taking benefits or reach age 70 – the age at which these delayed retirement credits stop accruing. Plus, your benefit also will increase by any cost-of-living adjustments applied to benefit payment levels during that time.4

If you intend to continue working, you may still receive the full benefit for which you are eligible. Indeed, working beyond full retirement age can increase your benefits. However, your benefits will be reduced if your earnings exceed certain limits. If you work and start receiving benefits before full retirement age, your benefits will be reduced by $1 for every $2 in earnings above the prevailing annual limit ($23,400 in 2025).5

If you continue to work during the year in which you attain full retirement age, your benefits will be reduced by $1 for every $3 in earnings over a different annual limit ($62,160 in 2025) until the month you reach full retirement age.5

Once you have attained full retirement age, you can keep working, and your benefits under current law will not be reduced regardless of how much you earn.5

As you can see, the decision of when to begin taking Social Security is a critical one.

3. Social Security May Be Taxable

Depending on your income level, your Social Security benefit may be subject to taxation. The chart below illustrates how your combined income (adjusted gross income + your nontaxable interest + one-half of your Social Security benefit) can impact whether your Social Security retirement benefit is subject to taxation.6

Will Your Social Security Benefits Be Subject to Federal Income Taxes?
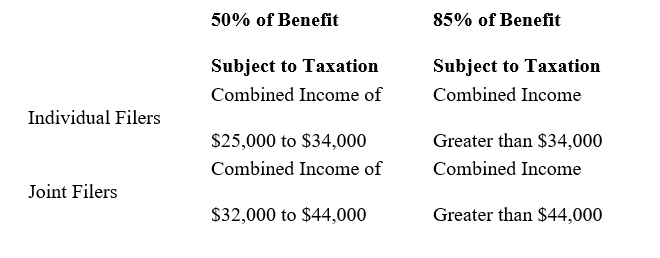
This potential income tax exposure may have substantial implications for whether you choose to work during retirement, how your assets are invested, and the timing of withdrawals from other retirement accounts.7,8

For instance, a withdrawal from a traditional IRA may lift your income beyond the thresholds described above, subjecting a higher proportion of your Social Security to income tax.7,8

The same is true of investment earnings in non-retirement savings. Retirees who have investment earnings in excess of their current spending needs may be subjecting their Social Security income to taxation. Shifting a portion of those assets to a tax-deferred instrument may be one way to manage taxation on your Social Security benefit.9

4. Social Security Can Be a Family Benefit

When you start receiving Social Security, other family members may also be eligible for payments. A spouse (even if they did not have earned income) qualifies for benefits if they are age 62 or older – or at any age if they are caring for your child. (The child must be younger than 16 or disabled.)

Benefits may also be paid to your unmarried children if they are younger than 18, between 18 and 19 and enrolled in a secondary school as a full-time student, or age 18 or older and severely disabled.

Each family member may be eligible for a monthly benefit that is up to half of your retirement (or disability) benefit amount. There is a family limit, which varies, but is generally between 150% to 188% of your retirement (or disability) benefit.10

Should you die, your family may be eligible for benefits based on your work record.10

Family members who qualify for benefits include:

  • A widow or widower
    • age 60 or older;
    • age 50 and older if disabled; or
    • any age if they are caring for your child who is younger than 16 or disabled and entitled to Social Security benefits on your record.
  • Unmarried children can receive benefits if they are:
    • under 18 years of age;
    • between 18 and 19 and are full-time students in a secondary school; or
    • age 18 or older and severely disabled (the disability must have started before age 22).

Your survivors receive a percentage of your basic Social Security benefit – usually in the range of 75% to 100% for each member. However, the limit paid to each family is about 150% to 188% of your benefit rate.10

5. A Divorced Spouse May Be Eligible for Benefits

If you are divorced, you may qualify for Social Security benefits based on your ex-spouse’s work record. To be eligible for benefits, your ex-spouse must have reached the age at which they are eligible to begin receiving benefits (although they do not necessarily need to be receiving them).10

To qualify, you need to:

  • have been married to your ex-spouse for at least 10 years;
  • have been divorced for two years or longer;
  • be at least 62 years old;
  • be unmarried; and
  • not be entitled to a higher Social Security benefit based on your own work history.

If your former spouse is deceased, you may still receive benefits as a surviving divorced spouse (irrespective of the age they died), assuming that your ex-spouse was entitled to Social Security benefits, your marriage was at least 10 years, you are at least 60 years old, and you are not entitled to a higher benefit amount based on your own work history. If you remarry before the age of 60, you will lose the ability to receive a survivor benefit from your deceased ex-spouse.10

If your former spouse is living, the maximum amount that you are eligible to receive is 50% of what your former spouse is due at full retirement age. To receive the maximum benefit, you will need to wait until you have reached your own full retirement age.10

Your benefits are unaffected should your former spouse elect to take Social Security before reaching full retirement age or if your ex-spouse starts a new family.10

1. EBRI.org, 2024
2. SSA.gov, 2024
3. SSA.gov, 2024
4. SSA.gov, 2024
5. SSA.gov, 2024
6. SSA.gov, 2024
7. In most circumstances, once you reach age 73, you must begin taking required minimum distributions from a Traditional Individual Retirement Account (IRA). You may continue to make tax-deductible contributions to a Traditional IRA past age 70½ as long as you meet the earned-income requirement.
8. Once you reach age 73 you must begin taking required minimum distributions from a Traditional Individual Retirement Account in most circumstances. Withdrawals from Traditional IRAs are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty.
9. The guarantees of an annuity contract depend on the issuing company’s claims-paying ability. Annuities have contract limitations, fees, and charges, including account and administrative fees, underlying investment management fees, mortality and expense fees, and charges for optional benefits. Most annuities have surrender fees that are usually highest if you take out the money in the initial years of the annuity contact. Withdrawals and income payments are taxed as ordinary income. If a withdrawal is made prior to age 59½, a 10% federal income tax penalty may apply (unless an exception applies).
10. SSA.gov, 2024
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Most women don’t shy away from the day-to-day financial decisions, but some may be leaving their future to chance.

Nearly 60% of women take the lead in managing their household finances, yet only 19% of women feel very confident in their ability to fully retire with a comfortable lifestyle.1,2

These figures suggest that most women don’t shy away from the day-to-day financial decisions needed to run a household, but when it comes to projecting and strategizing for retirement, some women may be leaving their future to chance.

Women and College

The reason behind this disparity doesn’t seem to be a lack of education or independence. Today, women are more likely to go to college than men. So what keeps them from taking charge of their long-term financial picture?3

One reason may be a lack of confidence. One study found that only 48% of women feel confident about their finances. Women may shy away from discussing money because they don’t want to appear uneducated or naive and hesitate to ask questions as a result.4

Insider Language

Since Wall Street traditionally has been a male-dominated field, women whose expertise lies in other areas may feel uneasy amidst complex calculations and long-term financial projections. Just the jargon of personal finance can be intimidating: 401(k), 403(b), fixed, variable. To someone inexperienced in the field of personal finance, it may seem like an entirely different language.5

But women need to keep one eye looking toward retirement since they may live longer and could potentially face higher healthcare expenses than men.

If you have left your long-term financial strategy to chance, now is the time to pick up the reins and retake control. Consider talking with a financial professional about your goals and ambitions for retirement. Don’t be afraid to ask for clarification if the conversation turns to something unfamiliar. No one was born knowing the ins and outs of compound interest, but it’s important to understand in order to make informed decisions.

Compound Interest: What’s the Hype?

Compound interest may be one of the greatest secrets of smart investing. And time is the key to making the most of it. If you invested $250,000 in an account earning 6%, at the end of 20 years, your account would be worth $801,784. However, if you waited 10 years, and then started your investment program, you would end up with only $447,712.

This is a hypothetical example used for illustrative purposes only. It does not represent any specific investment or combination of investments.

1. Yahoo.com, March 21, 2023
2. TransAmericaCenter.org, November 7, 2023
3. Statista, 2024
4. Bankrate.com, April 10, 2023
5. Distributions from 401(k), 403(b), and most other employer-sponsored retirement plans are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty. Generally, once you reach age 73, you must begin taking required minimum distributions.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

This checklist can give you a quick snapshot of how prepared you are.

Getting ready for retirement? Before you can cross that bridge, you’ll need to cross some important items off your to-do list. But thanks to our work together, you might be more prepared than you think! This handy checklist of ten crucial steps can help you visualize how far you’ve come.

Nice! You’re steps closer to retirement readiness.

Retirement Budget
Understand what your income will be, and how you can confidently spend the money you have accumulated for retirement.

Emergency Savings
Prepare for emergencies by saving at least 3 months’ living expenses, and have that money easily available to you.

Tax Strategy
Have a sound tax strategy to guide you through the process of spending money from both taxable and tax-deferred accounts.

Lifestyle & Location
Consider where you’ll live, both short- and long-term. Have a plan for funding a move and understand the timing involved.

401k Strategy
Have a strategy for your 401(k) plan and determine the best time for you to access the money, based on your goals.1

Bucket List
Write down your personal goals for your retirement years. Explore your dreams, priorities and values.

Extended Care
Make arrangements in the event that you or a loved one encounters a health issue requiring full-time care.

Estate Strategy
Develop an estate approach that includes how you want your assets to be allocated, and who will handle your estate.

Health Insurance
Understand your options with Medicare and define a strategy for covering health care expenses for the long haul.

Social Security Strategy
Have a sound tax strategy to guide you through the process of spending money from both taxable and tax-deferred accounts.

NOT QUITE READY?

If you’re not as prepared for retirement as you’d like to be, just reach out. Together, we can fine-tune these strategies so you can finish your checklist and get started on that bucket list.

1. Distributions from 401(k) plans and most other employer-sponsored retirement plans are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty. Generally, once you reach age 73, you must begin taking required minimum distributions.

Use this handy, informative article to help your clients understand Qualified Charitable Distributions (QCDs).

As you build your legacy, considering how to leverage your charitable contributions can be a fulfilling endeavor. Qualified Charitable Distributions (QCDs) can offer an opportunity to support your favorite causes and manage your retirement income. Here are some factors to consider with QCDs and how they’ve changed based on recent legislation, such as the SECURE Act.

What Is a Qualified Charitable Distribution (QCD)?

A Qualified Charitable Distribution allows individuals aged 70½ or older to donate directly from specific retirement accounts to qualified charities without recognizing the distribution as taxable income. Such distributions can help you manage your required minimum distributions (RMDs), which are required starting at age 73.

Remember, this article is for informational purposes only and is not a replacement for real-life advice. We encourage you to consult with your tax, legal, and accounting professionals before modifying your retirement income strategy.1

Age and Account Requirements

You must be at least 70½ years old to qualify for a QCD. The distribution can be made from an IRA. You can use SEP IRAs or SIMPLE IRAs so long as they are inactive, meaning that you’ve made no contributions to the account in the year the QCD is taken. However, keep in mind that 401(k)s and other non-IRA retirement vehicles do not qualify for QCDs.

Once you reach age 73, you must begin taking RMDs from a traditional IRA, SEP IRA, or SIMPLE IRA in most circumstances. Withdrawals from traditional IRAs are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty.

To qualify for the tax- and penalty-free withdrawal of earnings, Roth IRA distributions must meet a 5-year holding requirement and occur after age 59½. Tax-free and penalty-free withdrawals can also be taken under certain other circumstances, such as the owner’s death. The original Roth IRA owner is not required to take minimum annual withdrawals.1

Limits and Adjustments

The maximum annual limit for QCDs is currently set at $108,000 for 2025, an amount that adjusts for inflation yearly. Therefore, staying updated on the annual cap is important, as it can influence your donation strategy.1

Financial Advantages

In addition to helping you support a charity, a QCD may also offer to help you manage your tax situation. IRA withdrawals are generally taxable, but QCDs are excluded from taxable income, meaning they don’t increase your adjusted gross income (AGI). For some, this may be an opportunity to consider when balancing supporting a charitable organization and managing taxes.

Additionally, QCDs enable you to satisfy your RMD requirements. You also benefit from the fact that you don’t need to itemize deductions to take advantage of a QCD, allowing you to use the standard deduction.1

Again, this article is for informational purposes only. Speak with your tax, legal, and accounting professionals if you have specific questions about your deductions.

Charity and RMD Considerations

QCDs are versatile in that there is no restriction on the number of charities you can support, provided they qualify under IRS guidelines. However, the donation must go directly from your IRA to the charity to be a QCD. Gifts made as QCDs can fulfill all or part of your annual RMD requirement. It’s worth noting that if you donate over your RMD amount, the excess cannot be rolled over to the next year’s RMD.

Final Key Details

It’s prudent to confirm the status of your chosen charity through the IRS Online Search Tool or by consulting with a professional who can speak to the tax status of the organization. If you withdraw and then donate the funds, it does not count as a QCD and becomes taxable.

As with most financial strategies, your state may have specific rules impacting how QCDs are treated. It’s vital to check with a tax professional about state-specific regulations.

1. IRS.gov, 2025
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Learn about the latest sport to sweep the nation with this informative article.

Staying Active in Retirement

Over the last couple of years doctors have made clear the benefits of regular physical activity, especially for older adults. In fact, adults 65 and older gain substantial health benefits from regular physical activity. Being physically active can increase mobility, lessen the chance of injury, and lead to an overall better quality of life.1

The benefits of exercise extend beyond the physical though. Regular exercise also lowers the risk of dementia and reduces the symptoms of anxiety and depression. Even knowing all the advantages associated with staying active, it can be tough to find an activity that’s fun, mentally challenging, and physically taxing.2

A Nation of Pickleballers

But if having fun, engaging in friendly competition, and burning calories sounds like your kind of exercise, pickleball may be the sport for you. With over 4.8 million people in the U.S. playing pickleball right now, this fast growing sport is quickly becoming the favorite of active retirees nationwide.3
Where did it come from?

In 1965, Congressman Joel Pritchard and his close friend Bill Bell invented the game as a means to give their families something to do on vacation. Using an old badminton court, they improvised a game using ping-pong paddles and a perforated plastic ball. Over the course of a couple weeks, their family and friends discovered that this strange new game was tons of fun!4

How do you play?

Pickleball is played either as doubles (two players per team) or singles, but doubles is most common. This doesn’t mean you have to bring a partner though. Many leagues and communities have members that are more than happy to play with new teammates.

A standard pickleball play area is the same size as a doubles badminton court and measures 20×44 feet with the net set at tennis court height. There are a number of easy to grasp rules, but the biggest difference between pickleball and tennis is the “serve” and the “kitchen.”

In pickleball, the serve is made underhand and paddle contact with the ball must be below waist level. Much like tennis, the serve is made diagonally crosscourt and must land within the confines of the opposite diagonal court.5

“The kitchen” is a colloquial term for the non-volley zone. This is a 3.5-foot wide section of the court closest to the net and extends to each sideline. It’s not uncommon to hear yells of “Kitchen!” followed by roars of “Ohhhh!” or bellows of laughter during a game. Even seasoned players can find themselves celebrating a great volley, only to realize they’re standing squarely in “the kitchen” where volley’s are a big no-no.

Fun for Everyone

Because pickleball rules are so similar to ping-pong, the barrier to entry can be quite low. Grandparents, grandchildren, and anyone in between can pick up this fun game with little frustration. So next time you’re looking for something to break up the monotony of your normal exercise routine, why don’t you give pickleball a try? Whether you’re a beginner who just wants to learn a new sport for fun, or a seasoned athlete who craves the thrill of competitive play, pickleball offers something for everyone.

1. CDC.gov, 2022
2. CDC.gov, 2022
3. USAPickleBall.org, 2022
4. USAPickleBall.org, 2022
5. USAPickleBall.org, 2022
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.
css.php