Here are five facts about Social Security that are important to keep in mind.

Social Security can be complicated, and as a result, many individuals don’t have a full understanding of the choices they may have. Here are five facts about Social Security that are important to keep in mind.

1. Social Security Is a Critical Source of Retirement Income

Some have the perception that Social Security is of secondary or even tertiary importance in retirement. But according to a recent report by the Employee Benefits Research Institute, Social Security represents a major source of income for 62% of retirees.1

Keep in mind that Social Security makes annual cost-of-living adjustments (COLAs) based on the Consumer Price Index, and under current laws, pays income for life and the life of your spouse.2

2. You Can Choose When You Take Social Security

You have considerable flexibility regarding when you can begin receiving your benefits. You may begin receiving benefits as early as age 62; however, your benefits will be reduced at a rate of about one-half of 1% for each month you begin taking Social Security before your full retirement age.3

The full retirement age is 67 if you were born in 1960 or later. If you were born before 1960, your retirement age will be reduced depending on the year in which you were born.

You may choose to delay receiving benefits until after reaching your full retirement age; in which case, your benefits are scheduled to increase by 8% annually. This increase under current law will be automatically added each month from the moment you reach full retirement age until you start taking benefits or reach age 70 – the age at which these delayed retirement credits stop accruing. Plus, your benefit also will increase by any cost-of-living adjustments applied to benefit payment levels during that time.4

If you intend to continue working, you may still receive the full benefit for which you are eligible. Indeed, working beyond full retirement age can increase your benefits. However, your benefits will be reduced if your earnings exceed certain limits. If you work and start receiving benefits before full retirement age, your benefits will be reduced by $1 for every $2 in earnings above the prevailing annual limit ($23,400 in 2025).5

If you continue to work during the year in which you attain full retirement age, your benefits will be reduced by $1 for every $3 in earnings over a different annual limit ($62,160 in 2025) until the month you reach full retirement age.5

Once you have attained full retirement age, you can keep working, and your benefits under current law will not be reduced regardless of how much you earn.5

As you can see, the decision of when to begin taking Social Security is a critical one.

3. Social Security May Be Taxable

Depending on your income level, your Social Security benefit may be subject to taxation. The chart below illustrates how your combined income (adjusted gross income + your nontaxable interest + one-half of your Social Security benefit) can impact whether your Social Security retirement benefit is subject to taxation.6

Will Your Social Security Benefits Be Subject to Federal Income Taxes?
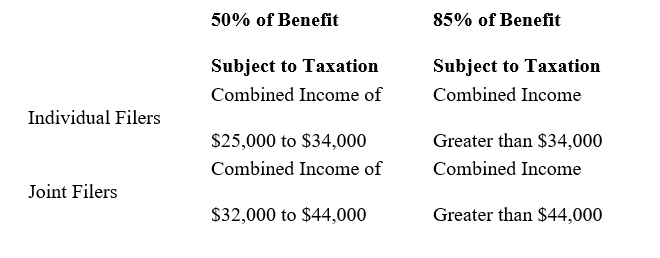
This potential income tax exposure may have substantial implications for whether you choose to work during retirement, how your assets are invested, and the timing of withdrawals from other retirement accounts.7,8

For instance, a withdrawal from a traditional IRA may lift your income beyond the thresholds described above, subjecting a higher proportion of your Social Security to income tax.7,8

The same is true of investment earnings in non-retirement savings. Retirees who have investment earnings in excess of their current spending needs may be subjecting their Social Security income to taxation. Shifting a portion of those assets to a tax-deferred instrument may be one way to manage taxation on your Social Security benefit.9

4. Social Security Can Be a Family Benefit

When you start receiving Social Security, other family members may also be eligible for payments. A spouse (even if they did not have earned income) qualifies for benefits if they are age 62 or older – or at any age if they are caring for your child. (The child must be younger than 16 or disabled.)

Benefits may also be paid to your unmarried children if they are younger than 18, between 18 and 19 and enrolled in a secondary school as a full-time student, or age 18 or older and severely disabled.

Each family member may be eligible for a monthly benefit that is up to half of your retirement (or disability) benefit amount. There is a family limit, which varies, but is generally between 150% to 188% of your retirement (or disability) benefit.10

Should you die, your family may be eligible for benefits based on your work record.10

Family members who qualify for benefits include:

  • A widow or widower
    • age 60 or older;
    • age 50 and older if disabled; or
    • any age if they are caring for your child who is younger than 16 or disabled and entitled to Social Security benefits on your record.
  • Unmarried children can receive benefits if they are:
    • under 18 years of age;
    • between 18 and 19 and are full-time students in a secondary school; or
    • age 18 or older and severely disabled (the disability must have started before age 22).

Your survivors receive a percentage of your basic Social Security benefit – usually in the range of 75% to 100% for each member. However, the limit paid to each family is about 150% to 188% of your benefit rate.10

5. A Divorced Spouse May Be Eligible for Benefits

If you are divorced, you may qualify for Social Security benefits based on your ex-spouse’s work record. To be eligible for benefits, your ex-spouse must have reached the age at which they are eligible to begin receiving benefits (although they do not necessarily need to be receiving them).10

To qualify, you need to:

  • have been married to your ex-spouse for at least 10 years;
  • have been divorced for two years or longer;
  • be at least 62 years old;
  • be unmarried; and
  • not be entitled to a higher Social Security benefit based on your own work history.

If your former spouse is deceased, you may still receive benefits as a surviving divorced spouse (irrespective of the age they died), assuming that your ex-spouse was entitled to Social Security benefits, your marriage was at least 10 years, you are at least 60 years old, and you are not entitled to a higher benefit amount based on your own work history. If you remarry before the age of 60, you will lose the ability to receive a survivor benefit from your deceased ex-spouse.10

If your former spouse is living, the maximum amount that you are eligible to receive is 50% of what your former spouse is due at full retirement age. To receive the maximum benefit, you will need to wait until you have reached your own full retirement age.10

Your benefits are unaffected should your former spouse elect to take Social Security before reaching full retirement age or if your ex-spouse starts a new family.10

1. EBRI.org, 2024
2. SSA.gov, 2024
3. SSA.gov, 2024
4. SSA.gov, 2024
5. SSA.gov, 2024
6. SSA.gov, 2024
7. In most circumstances, once you reach age 73, you must begin taking required minimum distributions from a Traditional Individual Retirement Account (IRA). You may continue to make tax-deductible contributions to a Traditional IRA past age 70½ as long as you meet the earned-income requirement.
8. Once you reach age 73 you must begin taking required minimum distributions from a Traditional Individual Retirement Account in most circumstances. Withdrawals from Traditional IRAs are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty.
9. The guarantees of an annuity contract depend on the issuing company’s claims-paying ability. Annuities have contract limitations, fees, and charges, including account and administrative fees, underlying investment management fees, mortality and expense fees, and charges for optional benefits. Most annuities have surrender fees that are usually highest if you take out the money in the initial years of the annuity contact. Withdrawals and income payments are taxed as ordinary income. If a withdrawal is made prior to age 59½, a 10% federal income tax penalty may apply (unless an exception applies).
10. SSA.gov, 2024
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Learn the advantages of a Net Unrealized Appreciation strategy with this helpful article.

Employer-issued stocks can be one attractive benefit an employer can offer. But while it has its benefits, it’s natural to wonder what happens if you leave that job.

That’s where net unrealized appreciation (NUA) strategies can sometimes be helpful. An understanding of NUA strategies can help you determine what to do with those company stocks to potentially manage your tax bill.

Remember, this article is for informational purposes only and is not a replacement for real-life advice. Make sure to consult your tax professional before modifying your approach with any unrealized appreciation issues.

Once your tax professional has provided guidance, your financial professional can offer insights regarding your overall asset allocation if you decide to realize any gains. Asset allocation is an approach to help manage investment risk. Asset allocation does not guarantee against investment loss.

What is Net Unrealized Appreciation (NUA)?

NUA is the difference between how much you paid or contributed to your company stock and its current market value. For example, if you were issued employer stock at $20 per share and it is now worth $50 per share, you would have an NUA of $30 per share ($50 – $20 = $30).

What are the NUA Rules?

Your NUA may be taxed differently than other payments. If the lump-sum distribution includes employer securities, the NUA may not be subject to tax until you sell the securities.1

With this in mind, a participant may be able to transfer company stock from their previous plan into a taxable investment account without treating the entire amount as ordinary income. But before exploring any choice in detail, seek the guidance of a tax professional while keeping your financial professional apprised of your decisions.

1.IRS.gov, January 23, 2023
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

Did you know that there are benefits and limitations when you decide to donate stock? Learn more about your options.

Key Takeaways

  • Some universities and major hospitals have huge endowments while your local shelter may struggle to keep its doors open. Sometimes finding smaller charities with bigger needs may increase the impact of your donation.
  • Donating stock can provide potential tax benefits, especially if you have owned the securities for at least one year.
  • While cash gifts are generally deductible up to 50% of adjusted gross income, the actual tax savings may vary based on your tax bracket and state taxes.

Why sell shares when you can gift them? If you have appreciated stocks in your portfolio, you might want to consider donating those shares to charity rather than selling them.

Donating appreciated securities to a tax-qualified charity may allow you to manage your taxes and benefit the charity. If you have held the stock for more than a year, you may be able to deduct from your taxes the fair market value of the stock in the year that you donate. If the charity is tax-exempt, it may not face capital gains tax on the stock if it sells it in the future.1

Keep in mind this article is for informational purposes only. It’s not a replacement for real-life advice. Make sure to consult your tax and legal professionals before modifying your gift-giving strategy.

“The greatest donor satisfaction may come with a combination of time and money.”

There are several reasons to consider donating highly appreciated stock to a tax-exempt charity. For example, you may own company stock and have the opportunity to donate some shares. There also are potential tax benefits to consider if you donate appreciated securities that you have owned for at least one year.

If you sell shares of appreciated stock from a taxable account and subsequently donate the proceeds from the sale to charity, you may face capital gains tax on any gain you realize, which effectively trims the benefit of cash donation.1

When is donating cash a choice to consider? If you provide the charity with a cash gift, there may be some limitations. Cash gifts are generally deductible up to 50% of adjusted gross income. As an example, if a donor in the top 37% federal tax bracket gives a 501(c)(3) non-profit organization a gift of $5,000, the net may be $3,150 with $1,850 realized in tax savings. A donor should also need to consider state taxes in addition to federal.2

If you donate shares of depreciated stock from a taxable account to a charity, you can only deduct their current value, not the value they had when you originally bought them.1

Picture1

Remember the tax rules for charitable donations. If you donate appreciated stock to a charity, you may want to review IRS Publication 526, Charitable Contributions. Double-check to see that the charity has non-profit status under federal tax law, and be sure to record the deduction on a Schedule A that you attach to your 1040.1

If your contribution totals $250 or more, the donation must be recorded – that is, the charity needs to give you a written statement describing the donation and its value and whether it is providing you with goods or services in exchange for it.2

If your total deduction for all non-cash contributions in a tax year exceeds $500, then complete and attach Form 8283 (Noncash Charitable Contributions) to your 1040 when filing. If you donate more than $5,000 of property to a charity, you will need to provide a letter from a qualified appraiser to the charity (and by extension, the IRS) stating the monetary value of the gift(s).2

Gifting cash or other assets to an organization is a wonderful opportunity. But keep in mind that tax rules are constantly being adjusted, and there’s a possibility that the current rules may change. Make certain to consult your tax and legal professionals before starting a new gifting strategy.

1. IRS.gov, 2023
2. IRS.gov, 2023
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

A quick look at how federal income taxes work.

Taxpayers and businesses spend an estimated 7.1 billion hours a year complying with tax-filing requirements, which is worth $388 billion in economic value just to comply with tax regulations.1

As complex as the details of taxes can be, the income tax process is fairly straightforward. However, the majority of Americans would rather not spend time with the process, which explains why half hire a tax professional to assist in their annual filing.2

Remember, this material is not intended as tax or legal advice. Please consult a professional with tax or legal experience for specific information regarding your individual situation.

Getting Started

The tax process starts with income, and generally, most income received is taxable. A taxpayer’s gross income includes income from work, investments, interest, pensions, as well as other sources. The income from all these sources is added together to arrive at the taxpayer’s gross income.

What’s not considered income? Gifts, inheritances, workers’ compensation benefits, welfare benefits, or cash rebates from a dealer or manufacturer.3

From gross income, adjustments are subtracted. These adjustments may include retirement plan contributions, half of self-employment, and other items.

The result is the adjusted gross income.

From adjusted gross income, deductions are subtracted. With deductions, taxpayers have two choices: the standard deduction or itemized deductions. The standard deduction amount varies based on filing status, as shown on this chart:

Chart Source: IRS.gov, 2025

Itemized deductions can include state and local taxes, charitable contributions, the interest on a home mortgage, and certain unreimbursed job expenses, among other things. Keep in mind that there are limits on the amount of state and local taxes that can be deducted.4

Once deductions have been subtracted, the result is taxable income. Taxable income leads to gross tax liability.

But it’s not over yet.

Any tax credits are then subtracted from the gross tax liability. Taxpayers may receive credits for a variety of items, including energy-saving improvements.

The result is the taxpayer’s net tax.

Understanding how the tax process works is one thing. Doing the work is quite another.

1. TTaxFoundation.org, August 27, 2025
2. IRS.gov, 2025
3. The tax code allows an individual to gift up to $19,000 per person in 2026 without triggering any gift or estate taxes. An individual can give away up to $15,000,000 without owing any federal tax. Couples can leave up to $30,000,000 without owing any federal tax. Also, keep in mind that some states may have their own estate tax regulations. This material is not intended as tax or legal advice. Please consult a professional with tax or legal experience for specific information regarding your individual situation.
4. The mortgage interest deduction is the first $750,000 of the loan for a home and the state and local income taxes deduction is capped at $40,400 for 2026.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

A company’s profits can be reinvested or paid out to the company’s shareholders as “dividends.”

When looking for income-generating investments, some investors turn to dividend-yielding stocks.

When a company makes a profit, that money can be put to two uses:

  1. It can be reinvested in the business.
  2. It can be paid out to the company’s shareholders in the form of a dividend, a taxable disbursement typically made quarterly or monthly.

Dividend Ratios

Investors track dividend-yielding stocks by examining a pair of ratios.1

Dividend per share measures how much cash an investor is scheduled to receive for each share of dividend-yielding stock. It is calculated by adding up the total dividends paid out over a year (not including special dividends) and dividing by the number of shares of stock that are outstanding.

Dividend yield measures how much cash an investor is scheduled to receive for each dollar invested in a dividend-yielding stock. It is calculated by dividing the dividends per share by the share price.

Other Dividend Considerations

Investing in dividend-paying stocks can create a stream of taxable income. But the fact that a company is paying dividends is only one factor to consider when choosing a stock investment.

Dividends can be stopped, increased, or decreased at any time. This is unlike interest from a corporate bond, which is normally a set amount determined and approved by a company’s board of directors. If a company is experiencing financial difficulties, its board may reduce or eliminate its dividend for a period of time. If a company is outperforming expectations, it may boost its dividend or pay shareholders a special one-time payout.
When considering a dividend-yielding stock, focus first on the company’s cash position. Companies with a strong cash position may be able to pay their scheduled dividend without interruption. Many mature, profitable companies are in a position to offer regular dividends to shareholders as a way to attract investors to the stock.

Qualified dividends are taxed at a maximum rate of 20%. Ordinary dividends are taxed at the same rate as federal income taxes, or between 10% and 37%. State income taxes also may apply.2

Be cautious when considering investments that pay a high dividend. While past history cannot predict future performance, companies with established histories of consistent dividend payment may be more likely to continue that performance in the future.

In a period of low interest rates, investors who want income may want to consider all their options. Dividend-yielding stocks can generate taxable income, but like most investments, they should be carefully reviewed before you commit any dollars.

Keep in mind that the return and principal value of stock prices will fluctuate as market conditions change. And shares, when sold, may be worth more or less than their original cost.

The information in this article is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation.

1. Investopedia.com, July 28, 2025
2. Investopedia.com, January 22, 2025
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG Suite is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.

The federal government requires deceased individuals to file a final income tax return.

When a family member passes away, there are many decisions that need to be made and many emotions to handle. The last thing anyone thinks about is taxes.

Unfortunately, even the deceased can’t escape taxation. If the departed family member earned taxable income during the year in which they died, then federal taxes may be owed. An executor or a survivor must, therefore, file a final federal income tax return (Form 1040).1

Similarly, if the deceased individual had a sizable estate or assets that might generate income in the future, the estate may owe taxes. Federal estate tax forms pertaining to the decedent’s estate may need to be filed (Form 1041, Form 706).2,3

The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult a professional with tax expertise if you find yourself in this situation.

Income Taxes

The Internal Revenue Service generally gives you until April 15 of the year following the taxpayer’s death to file a final 1040 form. If the deceased was married, a surviving spouse has the option to file a final joint federal tax return for the last year in which the deceased lived.4

If you file the return online, the IRS provides instructions on all of this. If you are filing a paper return, you must write “Deceased,” the decedent’s name, and the date of death at the top of the 1040 form. An appointed personal representative and/or surviving spouse must sign this return per IRS guidelines. If a refund is due, you may need to file a Form 1310 (Statement of Person Claiming Refund Due a Deceased Taxpayer).4,5

Estate Taxes

If an estate is large enough, Form 706 (the United States Estate Tax Return) is due to the IRS within nine months of the death of the deceased, with a 6-month extension permitted. The individual federal estate tax exemption is $15 million for 2026, so an estate smaller than $15 million may not be faced with estate taxes unless the deceased individual made substantial monetary gifts before their passing.6,7

When the decedent’s estate has an executor or administrator (in IRS terminology, an “appointed personal representative”), they must sign the return for the decedent. For a joint return, the spouse must also sign. Alternatively, a survivor of the deceased can file the return.4

If an estate generates more than $600 in gross yearly income within 12 months of that taxpayer’s death, it will also be necessary to file Form 1041 (U.S. Income Tax Return for Estates and Trusts), usually by April 15 of the year after the year in which the individual died. Should 100% of the income-generating assets of the deceased be exempt from probate, the need to file Form 1041 is removed. Estates required to file Form 1041 should consult a tax professional.8

Lastly, there are some cases where expenses paid before death can be deductible. Under certain circumstances, part of the cost of treating a final illness may be deducted from the deceased’s final federal tax return.9

You Are Not Alone

A death in the family can take a heavy toll. In the event of such a tragedy, the last thing you may want to do is deal with the related financial issues. Contact us – we are here to help.

1. IRS.gov, 2025
2. IRS.gov, 2025
3. IRS.gov, 2025
4. IRS.gov, 2025
5. Investopedia.com, July 8, 2025
6. IRS.gov, 2025
7. IRS.gov, 2025
8. IRS.gov, 2025
9. IRS.gov, 2025
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. FMG, LLC, is not affiliated with the named broker-dealer, state- or SEC-registered investment advisory firm. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright FMG Suite.
css.php